Ways to access emerging market debt

Feb 05, 2026

We introduce a framework to help investors consider the most suitable way to access EMD including benchmark relative and several benchmark agnostic strategies, including unconstrained, absolute return (long/short) and private credit.

Passive investment in EMD is sub-optimal and investors should tread carefully

EMD markets can, at times, be significantly inefficient and volatile with meaningful dispersion between the best and worst performing bonds. Passive investors could therefore be tied into highly volatile returns. In contrast, active investors are in a position to avoid the potential pitfalls associated with deteriorating credit developments and can employ downside protection strategies to mitigate negative periods in the market, allowing for a attractive risk-return profile.

Active funds can also benefit from a larger investable universe with the option of investing in off-benchmark positions. These may include bonds that lie outside the index yet offer higher risk-adjusted return potential, or bonds issued by smaller issuers that the index might not capture due to liquidity or other constraints defined by the index provider.

This is particularly relevant in the EM local currency market, which accounts for approximately 80% of the global EM debt universe1, yet the key indices only represent about 20% of the investable local market universe. This means the benchmark is highly concentrated amongst the high beta local currency markets and can be very volatile and not necessarily a true reflection of the overall sub-asset class. As a result, passive investors miss a vast opportunity to diversify outside of the benchmark and potentially boost returns.

A framework to help identify the most suitable active approach

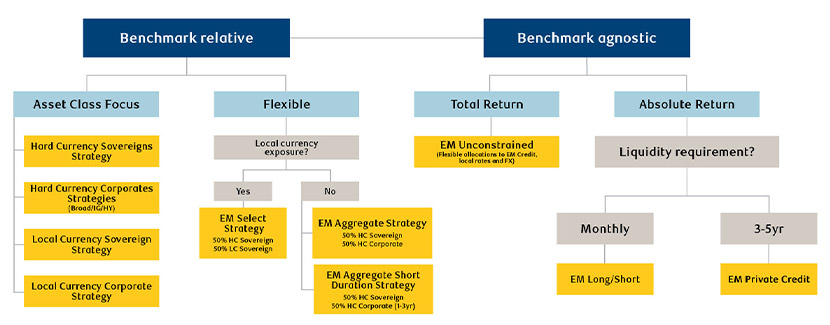
Below, we introduce a framework to help investors consider the most suitable way to access EMD, based on their requirements with respect to benchmark, liquidity, flexibility regarding asset class exposure and yield. We illustrate this spectrum in Figure 1, using the strategies we offer to our clients as examples.

Benchmark relative

  • Asset class focus: Investors who aim to gain exposure to the beta of a specific sub-asset class (e.g. to perform a specific role in a multi-manager portfolio or because of a strong view on certain asset classes), can invest in strategies where the manager seeks to outperform this sub-asset class benchmark over a cycle.
  • Flexible: Investors with more flexibility, but still seeking benchmark-relative returns, can target strategies which span multiple asset classes, but allow their active manager some flexibility to allocate between these sub-asset classes. These strategies aim to produced higher overall returns and lower volatility than holding separate single asset class investments as managers have an additional active lever to pull.

Benchmark agnostic

  • Total return, unconstrained (long-biased): These ‘go anywhere’ strategies are for investors who want the ability to capture the attractive upside available in EMD though a high conviction portfolio, but would like more flexibility to limit the downside during periods of high volatility, often using derivatives to manage risk quickly and efficiently. These are still long-biased solutions, but without the constraints of a market benchmark. They can help to smoothen the volatility of investments over the long term.
  • Absolute return, long/short (hedge fund): For investors who have the ability to allocate to long/short hedge funds, these strategies are similar to unconstrained strategies but have the added ability to short bonds. These are designed to be market neutral and generate strong positive returns irrespective of the underlying market environment. Typically, liquidity will be limited to monthly or longer and net return targets will be double-digits.
  • Private credit: For investors able to lock up their capital for multiple years, a private credit strategy can target 15+% gross and net IRR in excess of 12%, annualised. In an uncertain and volatile environment, when demand for EM corporate issuance may be unreliable, healthy corporates in EM often choose the private credit route for funding smaller or shorter maturity financing requirements, often at a premium versus their funding costs in the liquid, public markets. As a result, investors in EM private credit can earn a healthy premium whilst still focusing on higher quality credits. At times, private market lenders, particularly banks, will need to reduce their balance sheets for reasons unrelated to the specific underlying assets. Given the illiquid nature of the private credit markets within EM, this activity can cause temporary asset price dislocations. Investors in a position to take advantage of these dislocations can generate an additional return pick up in their private credit portfolios.
Figure 1: Finding the best solution for EMD exposures

Finding the best solution for EMD exposures

Source: RBC GAM, as at December 2024


1  RBC Global Asset Management as of 31 December 2024.

Iscriviti per ricevere gli approfondimenti via mail

Iscriviti ora per ricevere gli ultimi approfondimenti economici e sugli investimenti dei nostri esperti, inviati direttamente alla tua casella di posta elettronica.

Il presente materiale è fornito da RBC Global Asset Management (RBC GAM) a soli fini informativi e non può essere riprodotto, distribuito o pubblicato senza il previo consenso scritto di RBC GAM o delle sue società collegate qui indicate. Il presente materiale non costituisce un'offerta o una sollecitazione all'acquisto o alla vendita di alcun titolo, prodotto o servizio in alcuna giurisdizione; né è inteso a fornire consulenza di investimento, finanziaria, legale, contabile, fiscale o di altra natura, e tali informazioni non devono essere utilizzate o considerate come base per la prestazione di tale consulenza. Il presente materiale non è disponibile per la distribuzione a investitori residenti in giurisdizioni in cui tale distribuzione sia vietata.


RBC GAM è la divisione di asset management di Royal Bank of Canada (RBC) che include RBC Global Asset Management Inc. (RBC GAM Inc.), RBC Global Asset Management (U.S.) Inc. (RBC GAM-US), RBC Global Asset Management (UK) Limited (RBC GAM-UK) e RBC Global Asset Management (Asia) Limited (RBC GAM-Asia), le quali sono controllate separate ma collegate di RBC.


In Canada, il presente materiale è fornito da RBC GAM Inc. (inclusa PH&N Institutional), regolamentata da ciascuna commissione provinciale e territoriale sui titoli. Negli Stati Uniti (USA), il presente materiale è fornito da RBC GAM-US, un consulente d'investimento registrato a livello federale. Nel Regno Unito (UK) e in Australia, il presente materiale è fornito da RBC GAM-UK, autorizzata e regolamentata dalla Financial Conduct Authority del Regno Unito. Nello Spazio Economico Europeo (SEE), il presente materiale è fornito da BlueBay Funds Management Company S.A. (BBFM S.A.), regolamentata dalla Commission de Surveillance du Secteur Financier (CSSF). In Germania, Francia, Svezia, Italia, Spagna e Paesi Bassi, BBFM S.A. opera con passaporto di succursale ai sensi della Direttiva sugli organismi di investimento collettivo in valori mobiliari (2009/65/CE) e della Direttiva sui gestori di fondi di investimento alternativi (2011/61/UE). In Spagna, BlueBay Funds Management S.A. è registrata presso la CNMV al n. 607. In Svizzera, il presente materiale è fornito da BlueBay Asset Management AG, dove il Rappresentante e Agente Pagatore è BNP Paribas Securities Services, Paris, succursale de Zurich, Selnaustrasse 16, 8002 Zurigo, Svizzera. In Giappone, il presente materiale è fornito da BlueBay Asset Management International Limited, registrata presso il Kanto Local Finance Bureau del Ministero delle Finanze giapponese. In Asia, il presente materiale è fornito da RBC GAM-Asia, autorizzata dalla Securities and Futures Commission (SFC) di Hong Kong.


Ulteriori informazioni su RBC GAM sono disponibili all'indirizzo www.rbcgam.com.


Il presente materiale non è stato esaminato da, né registrato presso, alcuna autorità di regolamentazione dei titoli o di altra natura e può, ove opportuno e consentito, essere distribuito dalle entità sopra elencate nelle rispettive giurisdizioni.


Tutte le informazioni relative alle prospettive economiche e d'investimento contenute nel presente materiale sono state compilate da RBC GAM a partire da diverse fonti. Le informazioni ottenute da terzi sono ritenute affidabili, ma alcuna dichiarazione o garanzia, espressa o implicita, viene resa da RBC GAM, dalle sue società collegate o da qualsiasi altra persona in merito alla loro accuratezza, completezza o correttezza. RBC GAM e le sue società collegate non si assumono alcuna responsabilità per eventuali errori od omissioni in tali informazioni.


Le opinioni qui contenute riflettono il giudizio e la thought leadership di RBC GAM e sono soggette a modifiche in qualsiasi momento. Tali opinioni sono fornite a soli fini informativi e non intendono costituire una consulenza d'investimento o finanziaria, né si deve fare affidamento su di esse o agire sulla loro base per la prestazione di tale consulenza. RBC GAM non si assume alcun obbligo o responsabilità di aggiornare tali opinioni.


RBC GAM si riserva il diritto, in qualsiasi momento e senza preavviso, di modificare, emendare o cessare la pubblicazione di queste informazioni.


I rendimenti passati non sono indicativi dei risultati futuri. Non è possibile investire direttamente in un indice.


Alcune delle dichiarazioni contenute nel presente materiale possono essere considerate dichiarazioni revisionali che forniscono aspettative o previsioni correnti su risultati o eventi futuri. Le dichiarazioni revisionali non costituiscono una garanzia di rendimenti o eventi futuri e comportano rischi e incertezze. Si raccomanda di non fare un affidamento indebito su tali dichiarazioni, poiché i risultati o gli eventi effettivi potrebbero differire materialmente da quelli descritti in tali dichiarazioni revisionali a causa di diversi fattori. Prima di prendere qualsiasi decisione di investimento, vi invitiamo a considerare attentamente tutti i fattori rilevanti.


® / TM Trademark(s) di Royal Bank of Canada. Utilizzati su licenza.
© RBC Global Asset Management Inc., 2026  

Iscriviti per ricevere gli approfondimenti via mail

Iscriviti ora per ricevere gli ultimi approfondimenti economici e sugli investimenti dei nostri esperti, inviati direttamente alla tua casella di posta elettronica.