I recently travelled to the Republic of Congo to get a sense of regional CEMAC dynamics. I was struck by the following:
- The regional fabric is fraying: CEMAC's shared currency and pooled reserves should be a source of strength, but regional reserves are below IMF recommended minimums for resource-dependent economies, and Cameroon, historically viewed a stabilising anchor, is mired in a political vacuum.
- The debt composition and governance risks: prior IMF conditionality pushed countries into expensive short-term domestic debt, creating new vulnerabilities. Meanwhile public finance management is a tangible concern across CEMAC.
- Congo’s encouraging pathways forward: Congo has outlined reforms including digitising tax and customs declarations, implementing a single treasury account by July 2026, and restructuring electricity, oil, and gas subsidies. It also has untapped resource potential in areas from mining to renewable energy.
- The next six-months are key for CEMAC: Several factors will align to create either transformation or crisis; IMF programme discussions with multiple countries, oil price stability providing temporary fiscal breathing room, political transitions creating windows for structural reforms, and heightened international investor focus.
Have you heard of the Sapeurs of Brazzaville? This remarkable movement of Congolese gentlemen (Sapeurs) and ladies (Sapeuses), known for their impeccable fashion sense and colourful dress code, represents something profound about the Central African region that most investors fail to grasp. I was reminded of this during my recent visit to Brazzaville, where I wanted to get a sense of the regional dynamics, as the Economic and Monetary Community of Central Africa (CEMAC) countries increasingly turn to international bond markets to address mounting liquidity needs.
Much like the Sapeurs themselves – who understand that true style requires both individual flair and collective appreciation – the six CEMAC countries face the delicate challenge of balancing national priorities with regional coordination. Smaller countries like the Republic of Congo might find it surprisingly easier to transform themselves compared to their larger-scale neighbours. Standing on the banks of the Congo River, one is struck by the contrast: this compact nation of 5.5 million people is dwarfed by its neighbour visible across the water, the Democratic Republic of Congo (DRC), a country with nearly 100 million inhabitants. Yet, for the success of countries like the Republic of Congo, the regional fabric is as important as individual efforts.
The regional fabric: threads coming apart
CEMAC presents a compelling case study in the complexities of monetary integration without fiscal harmony. This union comprises six countries: Cameroon, Central African Republic, Chad, Republic of Congo, Gabon and Equatorial Guinea. With a shared currency (CFA franc), pooled reserves managed by a common central bank (BEAC), and collective decision-making requirements for IMF programmes, the region's fabric should theoretically provide strength. Instead, what I found was a tapestry with several loose threads threatening to unravel the entire design.
My meetings with policymakers revealed the complex web of challenges facing CEMAC countries. Regional reserves stand at 3.8 months of import cover – below the IMF 5-month minimum recommended for resource-dependent economies. The IMF's regional assurance requirements create a particularly perverse dynamic; even if countries like the Republic of Congo, running primary fiscal surpluses, are willing and able to deliver on the IMF objectives, they cannot access programme financing unless the majority of member states demonstrate policy commitment.
Yet IMF support is needed to help tackle the debt challenge. For example, the Republic of Congo’s debt problem, with a debt-to-GDP ratio above 90%, stems from the 2014-2015 oil price shocks and large investment projects financed through pre-financing agreements. While these arrangements have since been declining, with only Trafigura remaining as a major player, and are expected to be fully paid back by 2027-2028, the country has not managed to rein in fiscal spending at a fast enough pace.
The leadership vacuum: Cameroon as the missing centrepiece
When it comes to other CEMAC countries, the question of engagement is often that of willingness and ability. In the case of Cameroon, the willingness might be there on the level of technocrats, but the ability to engage is questionable, given the political vacuum. Eight months after disputed elections, the country remains without an effective government, trapped in factional fighting between groups aligned with the president's wife and other power centres. Some regional market participants believe that the president himself is no longer functionally leading, and the position of the vice president remains vacant, with some locals citing the odds of military intervention at an uncomfortable 40%, creating a leadership vacuum that reverberates throughout the region.
This is particularly devastating because Cameroon traditionally served as the region's anchor – as one official stated, it "used to be like Ivory Coast". The country historically accessed international markets at the lowest regional rates and provided a stabilising influence. However, its current dysfunction leaves other countries scrambling for alternative financing while constraining regional policy coordination.
This contrasts sharply with what we've seen in successful African transformations. Countries like Benin and Ivory Coast managed to align technocratic competence with political will. The current minister of finance in the Republic of Congo is clearly trying to do the right thing on the technical level – implementing automatic payment systems, launching single treasury accounts, and pursuing energy sector reforms. However, the challenge remains achieving alignment at the policy level when regional coordination lacks vision and leadership.
The debt composition paradox and banking sector constraints
Another interesting structural issue I encountered was the unintended consequence of previous IMF conditionality. The Fund's insistence on zero ceilings for external borrowing during the last programme prevented new foreign borrowing at longer term. Instead, this pushed countries toward expensive domestic financing that is short term in nature, creating new vulnerabilities, with domestic debt now accounting for over 60% of total in countries like the Republic of Congo.
Countries face a difficult choice if they were to go on a new IMF programme: breach IMF conditionality by accessing longer-dated external markets and risk increasing their future external vulnerabilities, or maintain programme compliance while accumulating a domestic debt burden when local market liquidity is constrained. The prudential regulation of the Central African Banking Commission – the banking regulator and supervisor for CEMAC – limits banks to 30% sovereign exposure of total assets, and most institutions are already at or breaching this threshold. With French banks exiting (citing poor returns and high capital requirements) and domestic banks saturated with government paper, new financing capacity is severely constrained.
Public Finance Management (PFM): the systemic blind spot
One of my key concerns centred around tangible disconnects in basic government operations. Some senior policymakers I met emphasised how public finance management (PFM) remains problematic across CEMAC – including digital disconnects, off-budget spending concerns and arrears management. In the case of Congo, annualised expenditure on goods and services has jumped from 2.1% of GDP to 5.8% – an exceptional surge attributed largely to military expenditures, according to one of the officials at a multilateral institution. The treasury and central bank lack proper digital connectivity, still sending payments through paper-based systems. This creates fundamental disconnects that undermine financial oversight, with off-budget spending through bank-financed contractor arrangements creating substantial arrears that governments struggle to quantify.
Similar issues are observed in other CEMAC countries. For example, Fitch, in its report, noted that Gabon’s fiscal deficit has increased sharply from 3.7% in 2024 to 12.2% of GDP in 2025 due to a surge in capital expenditure to 11% of GDP. This is well above its prior years, putting substantial pressure on its public finances.
Low-hanging fruit and natural resource opportunities
Despite these challenges, Congo has found encouraging pathways forward. The finance minister outlined several ‘low-hanging fruit’ initiatives: digitisation of tax and customs declarations, implementation of a single treasury account by July 2026, and comprehensive energy sector reforms addressing electricity, oil, and gas subsidies. The political will exists at the highest level for these reforms, though administrative hurdles persist.
Like the Sapeurs, who transform humble fabrics into statements of aspiration and dignity, CEMAC countries possess remarkable potential for transformation, with untapped potential in mining, phosphates, agriculture, and renewable energy. Congo alone has the rare combination of gas, phosphates, and potash – making it potentially self-sufficient in fertiliser production while creating export opportunities.
Infrastructure projects like the bridge connecting Brazzaville and Kinshasa in neighbouring DRC represent transformational regional connectivity, while gas export projects across multiple countries offer economic diversification beyond oil dependence.
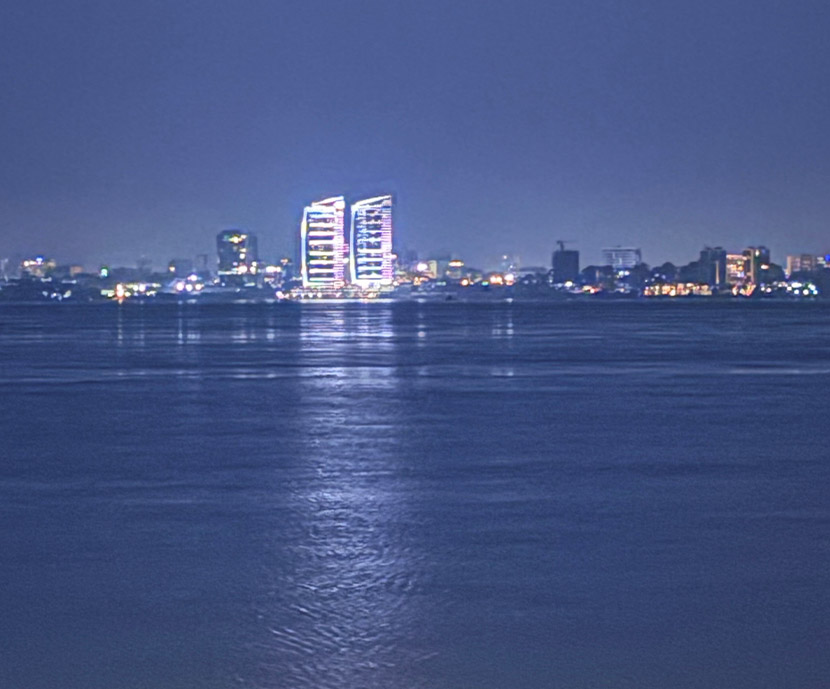
The view of Kinshasa across the river from Brazzaville
The next six months: a critical juncture
The coming period appears crucial for CEMAC's trajectory, with the next six months potentially determining the region's path. Several factors will align to create either transformation or crisis: IMF programme discussions with multiple countries, oil price stability providing temporary fiscal breathing room, political transitions creating windows for structural reforms, and heightened international investor focus on the region as the highest-yielding EM segment still performing. However, timely execution is essential.
Risks and opportunities: the investment perspective
On the positive side, higher oil prices provide fiscal space, while Italian development finance and other concessional financing could accelerate transformation, if properly utilised. The World Bank alone is providing $1 billion to Congo, with scope for expansion. More recently, some of the countries from the region were also able to access international markets ahead of the start of the IMF programme negotiations that temporarily eased their liquidity pressures.
The negative scenarios centre on regional fragmentation. If power transfer in Cameroon remains paralysed, and other countries continue accumulating debt through expensive international issuance and oil-backed deals (like the recent US$1bn oil-backed Trafigura deal with the government of Gabon), the whole region could face a confidence crisis. Indeed, this small segment of the emerging markets universe could tarnish outside perceptions of the broader emerging markets in a context where investors remain hypersensitive to potential defaults.
From an investment perspective, CEMAC represents the highest-yielding segment of EM debt that continues to perform – attracting continued investor focus despite challenges. However, significant differentiation is emerging between countries, based on governance and transparency standards. The spread differentials between countries pursuing proper disclosure and those opting for private placements without due diligence will only widen, as global fixed income allocations to emerging markets remain stubbornly low due to perceived volatility and default risks.
The Sapeurs’ paradox revisited
Returning to the Sapeurs and Sapeuses of Brazzaville, these remarkable individuals understand something profound about transformation: true elegance requires both individual excellence and collective recognition. They don't dress merely for personal satisfaction but to elevate their entire community's standards of aspiration and achievement.
The CEMAC region faces a similar challenge. Individual countries can pursue sound policies and achieve remarkable transformations – Congo's reform programme offers compelling evidence of this potential. But collective success requires simultaneous alignment across multiple dimensions: fiscal coordination, institutional strengthening, and shared commitment to transparency and good governance.
The Sapeurs of Brazzaville have mastered the delicate balance, transforming individual aspirations into collective achievement. The next six months will reveal whether their country – and the broader CEMAC region – can do the same. This remains the defining question for CEMAC's future.